



How Pakistani Freelancers Can Receive International Payments in 2026
TL;DR – What You’ll Learn
● Pakistan has 3M+ freelancers, but payment friction costs the sector hundreds of millions in lost fees and failed transfers every year.
● Payoneer is the most widely used option for Pakistani freelancers, but it carries a 2–3.99% fee depending on how you withdraw.
● Wise operates in Pakistan for receiving USD, GBP, and EUR, but functionality remains more limited than in Western markets.
● Bank wire (SWIFT) is reliable for large one-time payments, but costs $15–$30 per transfer and takes 3–5 business days.
● Upwork and Fiverr both support direct PKR bank deposits; understanding the platform’s withdrawal options can save you thousands annually.
● JazzCash and Easypaisa can receive inbound international remittances through select services, but are not yet a standalone withdrawal channel for most platforms.
● Freelance income remitted through banking channels qualifies for FBR’s preferential IT export tax scheme, a fact most freelancers miss entirely.
Pakistan has over 3 million active freelancers earning more than $1 billion annually, yet knowing how to accept online payments in Pakistan remains the single biggest bottleneck stopping talented professionals from scaling their income. Whether you are on Upwork, Fiverr, or working directly with international clients, choosing the wrong withdrawal method quietly eats into every payment you receive.
This guide breaks down every major option available in 2026: what it costs, how fast it moves, and where it falls short.
Pakistan’s 3 Million Freelancers – The Payment Problem
Pakistan consistently ranks among the top five freelancing nations globally, a position confirmed by data from the Payoneer Global Freelancer Survey and multiple World Bank financial inclusion reports. The government’s own e-Rozgaar program has trained over 130,000 freelancers across the country, and platforms like Upwork and Fiverr count Pakistan among their fastest-growing talent markets.
Yet the payment infrastructure has not kept pace. The problems are predictable and persistent:
● Fee leakage. On a $500 payment, a freelancer using the wrong withdrawal method can lose $20–$40 in fees before a single rupee hits their account.
● Delayed access. Bank wire transfers that take 3–5 business days are not just inconvenient, they are a cash-flow problem for freelancers managing monthly expenses in PKR.
● Currency conversion losses. Most Pakistani freelancers earn in USD but spend in PKR. A 1% difference in the exchange rate on a $1,000 payment equals roughly PKR 2,790 at current rates. Over time, these small differences can significantly impact total earnings.
● Platform friction. Pakistani banks are still not universally supported on global platforms. Freelancers routinely report failed withdrawals, incorrect routing numbers, and delayed settlements.
Knowing how to accept online payments in Pakistan and which method fits your specific workflow is not a minor administrative detail. It directly affects what you take home.
Method 1: Payoneer – Pros, Cons, Fees 2026
Payoneer is the most widely used payment method for Pakistani freelancers, and for good reason. It is accepted on Upwork, Fiverr, Freelancer.com, and dozens of other platforms as a first-party withdrawal channel. It supports direct payments from international clients who do not use any of those platforms.
Pros of Payoneer
Payoneer remains popular because it solves the basic problem of receiving international payments. It allows freelancers to operate globally without needing complex banking setups.
● Supports multiple currencies (USD, EUR, GBP)
● Widely accepted by platforms like Upwork, Fiverr, and Amazon
● Easy withdrawal to Pakistani bank accounts
● Simple onboarding and global accessibility
For freelancers just starting, Payoneer offers a reliable entry point into cross-border payments.
Cons of Payoneer
As usage grows, limitations become more visible. What starts as a convenient solution can turn into a cost-heavy system over time.
● Hidden charges through currency conversion margins
● Withdrawal delays depend on banks and processing cycles
● Limited flexibility in choosing payout routes
● Dependence on a single provider for all transactions
For freelancers with consistent income, these issues can directly affect monthly earnings and financial planning.
Fees in 2026: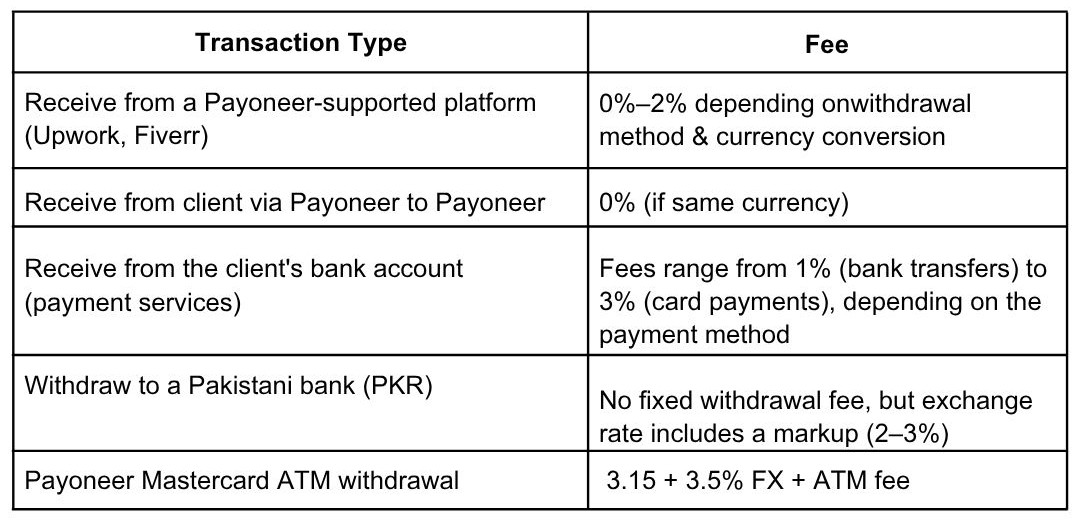
● Settlement time: 2–3 business days to a Pakistani bank account after Payoneer clears the funds.
● Withdrawal limit: Up to $50,000 per transaction for verified accounts.
● The real cost: On a $1,000 Fiverr payment, a freelancer receiving via Payoneer and withdrawing to their bank account typically loses $40–$60, depending on the PKR exchange rate used. Payoneer’s internal conversion rates have historically been 1–1.5% below the mid-market rate.
● Where Payoneer wins: Reliability, platform support, and the fact that it is accepted everywhere. For freelancers who receive multiple payments per month from different sources, consolidating into Payoneer keeps the workflow clean.
● Where it falls short: The cumulative fee burden on high-volume freelancers is significant. A freelancer earning $3,000/month is losing $90–$150 in Payoneer fees alone, roughly $1,500–$1,800 per year.
Method 2: Wise (TransferWise) – Is It Available for Pakistan?
Wise (formerly TransferWise) operates in Pakistan in a limited capacity as of 2026. Pakistani freelancers can receive USD, GBP, and EUR payments from international clients directly into a Wise account. However, the full Wise personal account, which provides local bank details in 9+ currencies, is not available to Pakistan-registered users in the way it is available to UK or US users.
What Pakistani freelancers can do with Wise:
● Receive international bank transfers sent to Wise’s corresponding accounts
● Hold balances in multiple currencies
● Convert and withdraw to a Pakistani bank account in PKR
What they cannot do:
● Open a standard multi-currency Wise account with a Pakistani address for all features
● Send international transfers from Pakistan through Wise as freely as users in supported countries
Fees: Wise typically charges around 0.5% to 1% for USD to PKR transfers, depending on the payment method and transfer size. Unlike providers that include hidden FX markups, Wise uses real exchange rates with transparent fees. For a $1,000 payment, this can result in savings of roughly $10 to $20 compared to traditional payout methods.
Practical use case: Wise works well for Pakistani freelancers with direct client relationships who invoice clients abroad. The client sends a bank transfer to Wise’s USD account details, and the freelancer converts and withdraws to their Pakistani bank.
Caution: Wise’s Pakistan support has evolved, and the availability of specific features can change. Always verify current functionality on Wise’s website before incorporating it into a client invoicing workflow.
Method 3: Bank Wire Transfer – SWIFT & IBAN
A direct SWIFT wire transfer from an international client to a Pakistani bank account is the oldest method and still appropriate in specific circumstances.
How it works: Your client’s bank sends USD, GBP, EUR, or AED directly to your Pakistani bank account using your SWIFT/BIC code, account number, and IBAN. The sending bank routes through a correspondent bank, which converts and credits your account in PKR.
Fees:
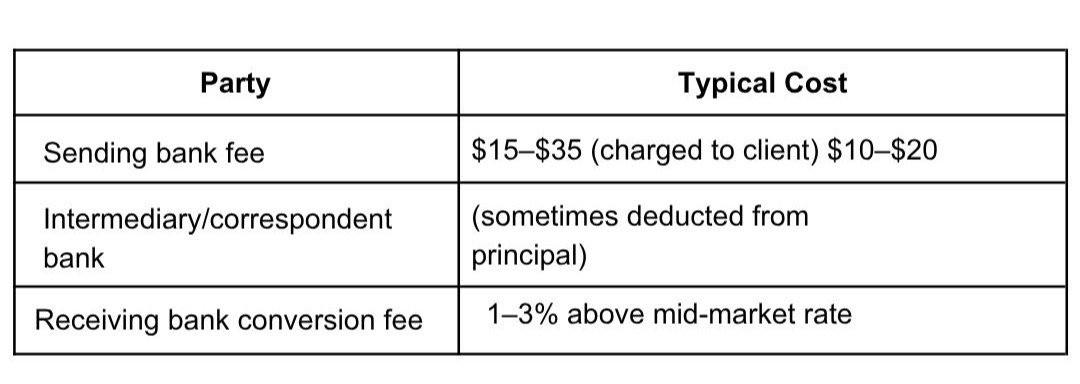
● Settlement time: 3–5 business days. HBL, MCB, UBL, and Meezan Bank all support incoming SWIFT wires.● When bank wire makes sense: For large single payments above $3,000–$5,000, the flat fee structure of SWIFT makes it more cost-effective than percentage-based platforms. A $5,000 SWIFT wire might cost $50–$80 total versus $150–$200 via Payoneer percentage fees.
● Challenges: SWIFT transfers require accurate routing information. One wrong digit in an IBAN causes rejection or delays. Pakistani banks also apply their own conversion rates, which may be less competitive than specialist platforms. For recurring small payments, the per-transfer fee makes SWIFT inefficient.
● Pro Tip: Ask your bank for their “TT buying rate” versus the interbank rate before deciding. The spread between what your bank offers and the mid-market rate on large transfers is often the hidden cost nobody discusses.
Method 4: Receiving via Platforms (Upwork, Fiverr) – Withdrawal Guide
For freelancers working on established platforms, the withdrawal method available directly inside the platform is often the most convenient and sometimes the most cost-effective.
Upwork withdrawal options for Pakistani freelancers (2026):
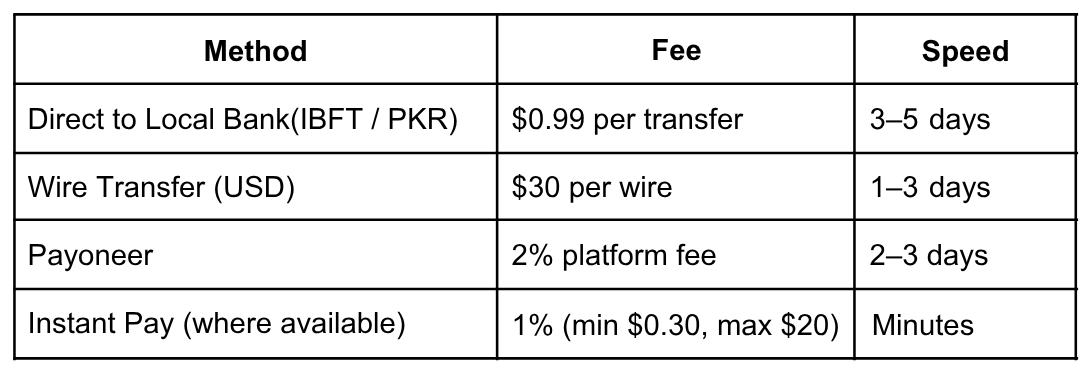
The direct-to-local-bank option via Upwork has been available to Pakistani freelancers and is worth using for lower withdrawal amounts, where the $0.99 flat fee beats percentage-based alternatives.
Fiverr withdrawal options for Pakistani freelancers (2026):
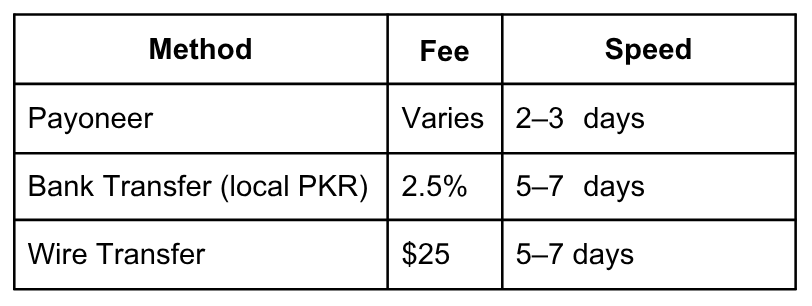
Fiverr’s local bank transfer option deposits directly into Pakistani accounts in PKR, which simplifies the process for freelancers who do not want to manage a Payoneer account.
Key insight: Both Upwork and Fiverr have a minimum earnings threshold before withdrawal (typically $100 for most methods). Accumulating earnings inside the platform before withdrawing reduces the per-transfer fee impact.
Method 5: Mobile Wallets (JazzCash, Easypaisa) – International Reception
JazzCash and Easypaisa, the two dominant mobile wallets in Pakistan with 40 million and 20 million registered users, respectively, are primarily domestic payment tools. However, both have expanded international inbound remittance support.
What is possible in 2026:
Certain international money transfer services, including WorldRemit, Remitly, and select exchange houses, can deliver funds directly to a JazzCash or Easypaisa wallet. This is primarily designed for the diaspora remittance use case, but is technically available to freelancers if their client uses a compatible send-side platform.
Limitations:
● You cannot “give a client your JazzCash number” and have them pay from a US bank account directly
● International platforms like Upwork and Fiverr do not support JazzCash/Easypaisa as withdrawal destinations (as of 2026)
● Wallet transaction limits apply: typically up to PKR 500,000/month for Level 2 accounts
Best use case for freelancers: If a client is in the UAE, Saudi Arabia, or the UK and wants to send a small payment quickly, directing them to use a service that delivers to JazzCash/Easypaisa wallets can work for one-off, lower-value transactions. For structured freelancing income, wallets are a secondary tool rather than a primary channel.
Tax & FBR Implications for Freelance Income in Pakistan
This is where most Pakistani freelancers leave significant money on the table through either overpaying tax or, more dangerously, non-compliance.
The IT Export Preferential Tax Scheme: Pakistan’s Federal Board of Revenue (FBR) has specific provisions for technology-based export income, including freelancing. Income remitted to Pakistan through banking channels from foreign clients, which covers Payoneer withdrawals, SWIFT, and direct bank transfers, is considered IT export income.
Under the Finance Act provisions applicable through 2026:
● IT export income remitted via banking channels is taxed at a reduced rate (1% withholding tax as final tax) rather than standard income tax slabs.
● This benefit only applies when funds are received through regulated banking channels or licensed payment providers. Informal transfer methods or off-record transactions do not qualify under FBR’s IT export provisions.
● Freelancers must file with FBR and declare their freelance income to benefit from this scheme.
Practical steps:
1. Register as an individual taxpayer on FBR’s Iris portal
2. Obtain a National Tax Number (NTN)
3. File annual income tax returns, including your foreign remittance income
4. Retain Payoneer/bank statements as proof of remittance channel
Caution on FBR changes: Tax policy in Pakistan changes frequently. The rates and conditions described here reflect the framework as understood through mid-2025. Consult a Pakistan-based tax advisor for current rates before filing.
SBP foreign currency rules: The State Bank of Pakistan requires that freelance income above certain thresholds be reported when repatriated. Using formal banking channels, not informal transfer methods, keeps you compliant with both SBP and FBR requirements.
Comparison Table: Fees, Speed, Limits for All Methods
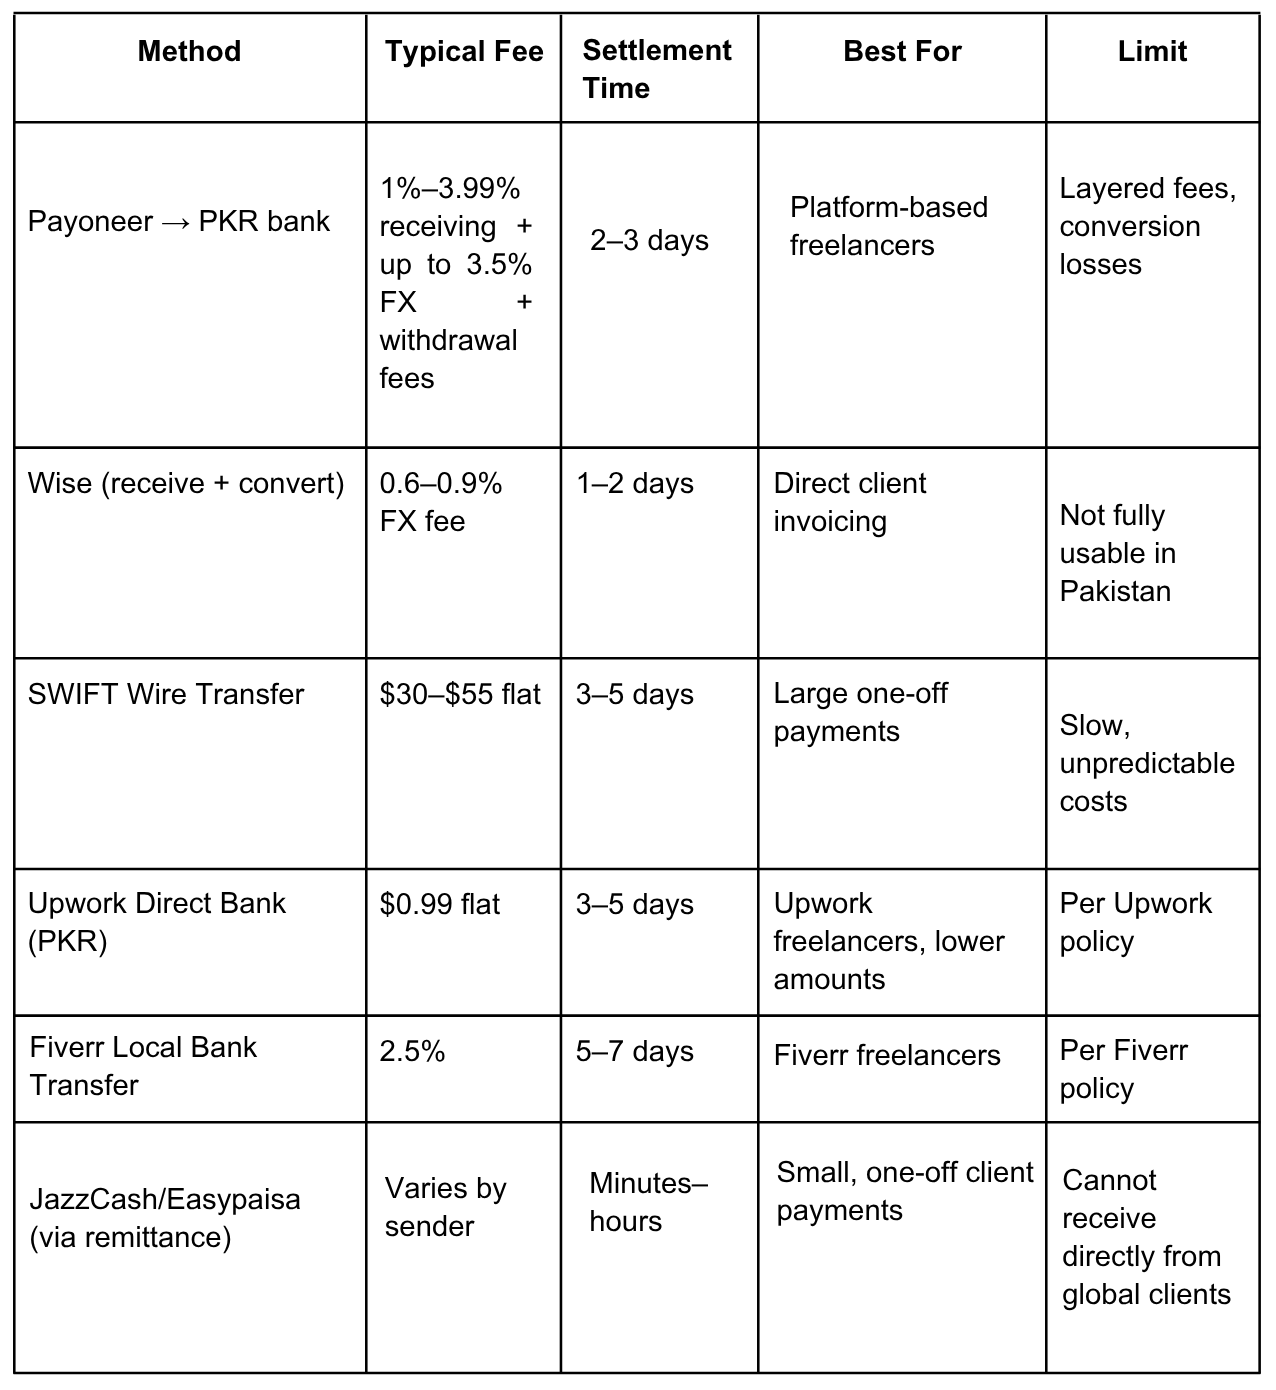
Rule of thumb: For payments below $500, platform-native methods or Payoneer are typically most convenient. For payments above $2,000, SWIFT or Wise may save $30–$80 per transfer. The “best” method depends on your volume, frequency, and whether you are on a platform or invoicing clients directly.
For Freelance Platforms: How to Disburse to Pakistani Freelancers
If you are building or operating a freelance marketplace, gig platform, or contractor management system that pays Pakistani talent, the operational challenge is the reverse: you need to disburse to tens, hundreds, or thousands of individuals across different banks and wallets reliably, at scale, and in compliance with SBP regulations.
The payments a freelancer receives as an individual are a small slice of the total money moving through this ecosystem. Platforms with 10,000+ Pakistani freelancers are collectively disbursing hundreds of millions of dollars annually, often manually, through fragmented processes that create reconciliation nightmares and delayed payouts.
The typical pain points platforms report:
● Multiple bank integrations. To pay Pakistani freelancers across HBL, MCB, Meezan, UBL, and other banks, plus JazzCash and Easypaisa wallet users, a platform would historically need separate relationships with each institution.
● File-based vs. API-based flows. Smaller platforms often use file uploads (CSV batches) while larger platforms require real-time API calls. Most banking providers support one model, not both.
● Failed payment handling. A bank account number typo or a wallet that has exceeded its monthly limit results in a failed transfer. Without automated retry logic and failure notifications, these end up in a manual queue, costing operations teams hours per week.
● FX settlement. International platforms disbursing in USD to a Pakistani bank account need to manage the USD-PKR conversion. Rates, timing, and settlement windows directly affect freelancers’ take-home income.
What high-performing platforms are doing instead is consolidating their Pakistani disbursements through a single integration that handles the routing, wallet mapping, and bank channel selection automatically connecting through one API to 98% of mobile wallet users and all major bank networks, without managing individual institution relationships.
Simpaisa’s Freelancer Disbursement Solution – B2B Angle
For platforms that pay Pakistani freelancers, the challenge is less about which method to use and more about building a disbursement system that scales without adding operational headcount.
Simpaisa’s disbursement infrastructure is built specifically for this use case. Through a single API integration, platforms can disburse to Pakistani bank accounts (across all major banks via IBFT), JazzCash wallets, and Easypaisa wallets using either API-based or file-based disbursement flows, depending on the platform’s technical architecture.
Key capabilities for freelance platforms:
● Bulk wallet disbursement to JazzCash and Easypaisa is simultaneously relevant for platforms where freelancers prefer wallet-based income for day-to-day spending.
● File-based batch upload for platforms that process weekly or monthly payment runs without dedicated development resources.
● Automated reconciliation with transaction-level reporting, eliminating the manual matching that currently consumes finance operations time.
● Failure handling and retry logic are baked into the integration rather than surfacing in your team’s inbox.
Explore how Simpaisa’s freelancer disbursement infrastructure works for platform operators, or review the full disbursing payouts product for technical integration details.
Conclusion
Pakistani freelancers have more options for receiving international payments in 2026 than at any point in the country’s history, but the difference between the best and worst options can easily cost $1,500+ per year in unnecessary fees and FX losses. The right choice depends on your volume, your platforms, and how you prefer to manage the PKR conversion.
The three most important takeaways:
1. For platform-based freelancers (Upwork, Fiverr), the platform’s own direct-to-bank option is often the cheapest for smaller withdrawals, as there is no need to run everything through Payoneer.
2. For direct client relationships with larger transfer amounts, Wise or SWIFT wire transfer reduces FX losses significantly compared to percentage-based services.
3. Register with FBR and use formal banking channels for all remittances. The IT export tax incentive is a real and legal way to reduce your effective tax rate, but it requires documented banking channel inflows.
For freelance platforms: Paying Pakistani freelancers at scale through fragmented, manual processes is not a payments problem; it is an infrastructure problem. The right disbursement partner consolidates all of it.
Running a freelance platform? Pay your Pakistani freelancers instantly via JazzCash, Easypaisa, or bank with a single Simpaisa Api integration. Get in touch with Simpaisa today.
Frequently Asked Questions
1. Can Pakistani freelancers receive PayPal payments in 2026?
No. PayPal’s send and receive functionality remains unavailable in Pakistan. Use Payoneer, Wise, or a direct bank wire transfer instead.
2. What is the maximum amount a Pakistani freelancer can receive through Payoneer per transaction?
Up to $50,000 per transaction for fully verified accounts. Monthly receiving limits are generally $100,000. Contact Payoneer directly for higher-volume arrangements.
3. Do I need to pay tax on freelance income I keep in Payoneer and never transfer to Pakistan?
Yes. Pakistani tax law taxes income when earned, not when repatriated. Keeping funds in Payoneer does not exempt you from FBR reporting obligations.
4. How long does it take to set up a Pakistani bank account for receiving international transfers?
Most major banks (HBL, MCB, UBL, Meezan) open an account within 1–3 days with a valid CNIC. SWIFT/IBAN details are typically available within 1–2 business days after activation.
5. Can a freelance platform based outside Pakistan pay its Pakistani contractors using JazzCash directly? Not without a licensed local infrastructure partner. International platforms must integrate with a licensed Payment Service Operator (PSO) to disburse directly to JazzCash or Easypaisa wallets in Pakistan.
